Citi Introduces “Once Per Lifetime Language” for Strata Cards, Replaced 1/48 Rule
Sep 22, 2026
Citi Introduces “Once Per Lifetime Language” for Strata Cards, Replaced 1/48 Rule


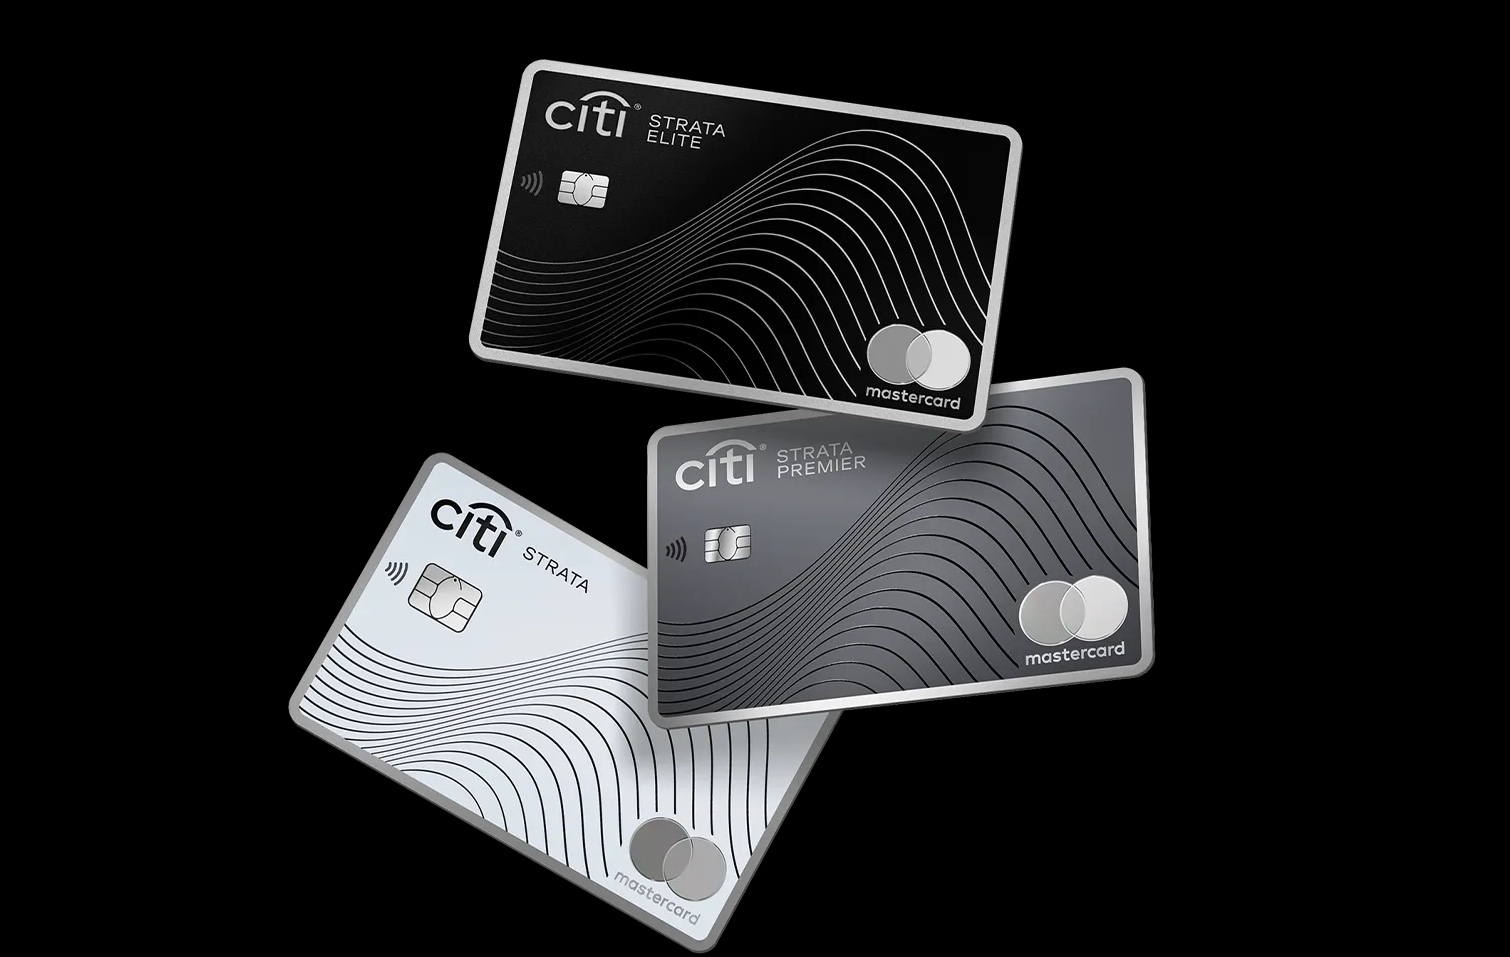
Citi has suddenly changed its welcome bonus eligibility terms, introducing AmEx-style “once-in-a-lifetime” language.Here’s an example from the Citi Strata Premier:

New account bonus offer is not available if you currently have or previously had a Citi Strata Premier® or a Citi Premier® account.You also may not be eligible for the new account bonus offer based on a number of factors, such as your history of opening, closing and using credit cards.

This new “once-in-a-lifetime” restriction replaces the previous Citi 1/48 rule, which required you to wait 48 months after receiving a welcome bonus before earning another bonus on the same card.

For now, the new terms only affect the Strata lineup:

Other Citi cards are not affected at this time.

Currently, this once-in-a-lifetime restriction is card-specific: holding or having held one Strata card does not affect your welcome bonus eligibility for the other cards in the lineup.

If you like this post, don't forget to give it a 5 star rating!

[Total: 0   Average: 0/5]

Disclaimer: This story is auto-aggregated by a computer program and has not been created or edited by mycardopinions.
Publisher: Source link

Leave a Reply

Your email address will not be published. Required fields are marked*

Frequently Asked Questions

Certainly. Unlike personal loans, you won't face any penalties for settling your balance ahead of schedule. However, it's crucial to keep in mind that if your credit card comes with a 0% introductory offer, it's essential to clear your balance completely before the 0% promotion expires and interest charges apply.
However, you can include additional cardholders, each with their own card. While sharing the single credit limit, the primary cardholder remains responsible for settling the debt.
Potentially, yes. Credit card APRs are typically variable, allowing lenders to change rates, impacting your monthly payments. Additionally, be mindful that introductory 0% offers can lead to higher interest rates once they expire. So, it's wise to clear your balance before that happens, if feasible.
Indeed, credit builder cards exist for those with less-than-ideal credit scores. These cards offer lower credit limits (typically £150 to £1,200) and higher interest rates. Responsible use, including full and on-time payments, can gradually boost your creditworthiness, potentially opening doors to better credit card offers down the line.

Site Search